
Free Loan Agreement Template
A loan agreement is a legal contract where a lender provides funds to a borrower, who agrees to repay the amount with interest. This document should detail the loan amount, repayment terms, any collateral offered, and conditions for default.
Protect your loan in minutes. What is the money for?
Fill forms in a few steps
Save, print & download
Done in 5 minutes
What Is a Loan Agreement?
A loan is an agreement between 2 parties in which one individual or business (known as the lender) lends money to the other party (in this case, the borrower) [1].
This sum is then paid back over weeks, months, or years.
The loan amount is usually returned to the lender in regular installments, and very often a percentage of interest is added to the original amount.
A Loan Agreement is used by these parties to create a clear record of the sum of money that is being lent, the terms of repayment, and any interest that is being levied on the amount.
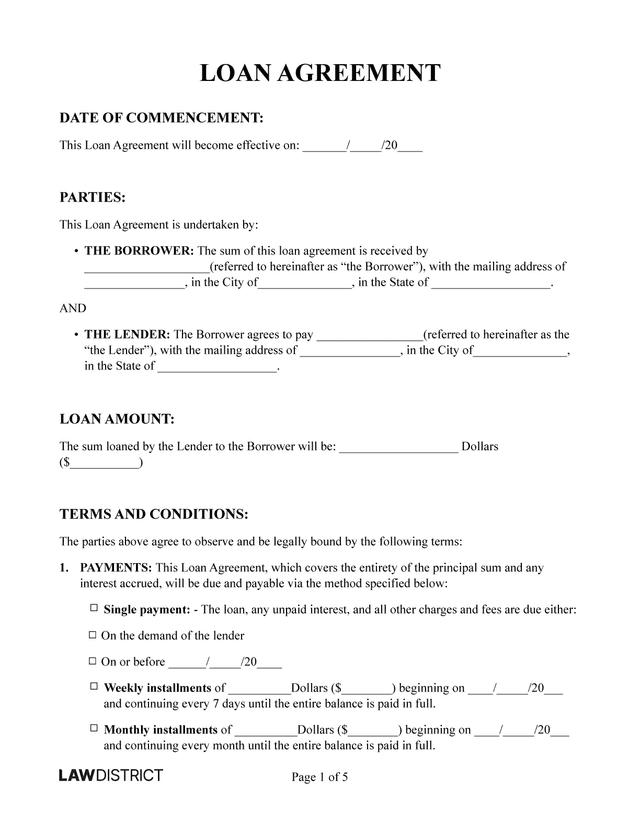
Loan Agreement Sample
Before you start writing and modifying your own Loan Agreement template, it can be helpful to look over a real-life example.
Types of Loan Agreement
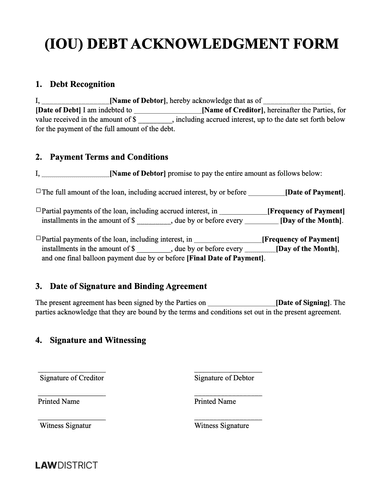
An IOU is an agreement made between a borrower and lender, also known as a friendly loan agreement because it is informal, but it can be used in court
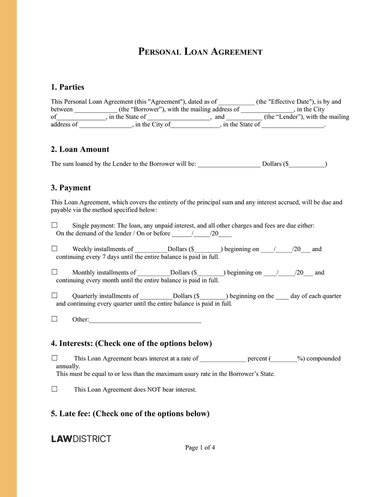
A personal loan agreement allows a borrower and a lender, such as a bank, credit union or online lender, to outline the details of the money being lent
Other Types of Loan Agreement
Some loan agreements cover specific borrowing arrangements. They can be offered by banks, credit unions, or other lenders. Here are three more common types:
| Loan type | What it is |
|---|---|
| Signature loan | An unsecured personal loan approved without collateral, usually based on the borrower’s creditworthiness and ability to repay. |
| Mortgage | A loan used to buy or refinance real estate, with the property serving as collateral for the lender. |
| Student loan | A loan used to cover education costs, offered through government programs, banks, credit unions, or other private lenders. |
Who Needs a Loan Agreement?
Anyone lending money should use a Loan Agreement. It’s legally enforceable, providing a clear record of the loan terms and protecting both parties in case of disputes.
For borrowers, a Loan Agreement specifies the repayment schedule and interest rates, ensuring transparency and protection against predatory practices and unexpected changes.
How To Write a Loan Agreement
There are a few important points to remember when you write a Loan Agreement.
First, you must use clear and easy-to-understand language so that it is immediately obvious who is who in the agreement and how the money should be repaid.
After all, a Loan Agreement is a legally enforceable contract, so it must be obvious to anyone reading it what the terms are and who the parties bound by it are [2].
There should be no ambiguity at any stage, or it could lack the clout necessary to hold a breaching party to account.
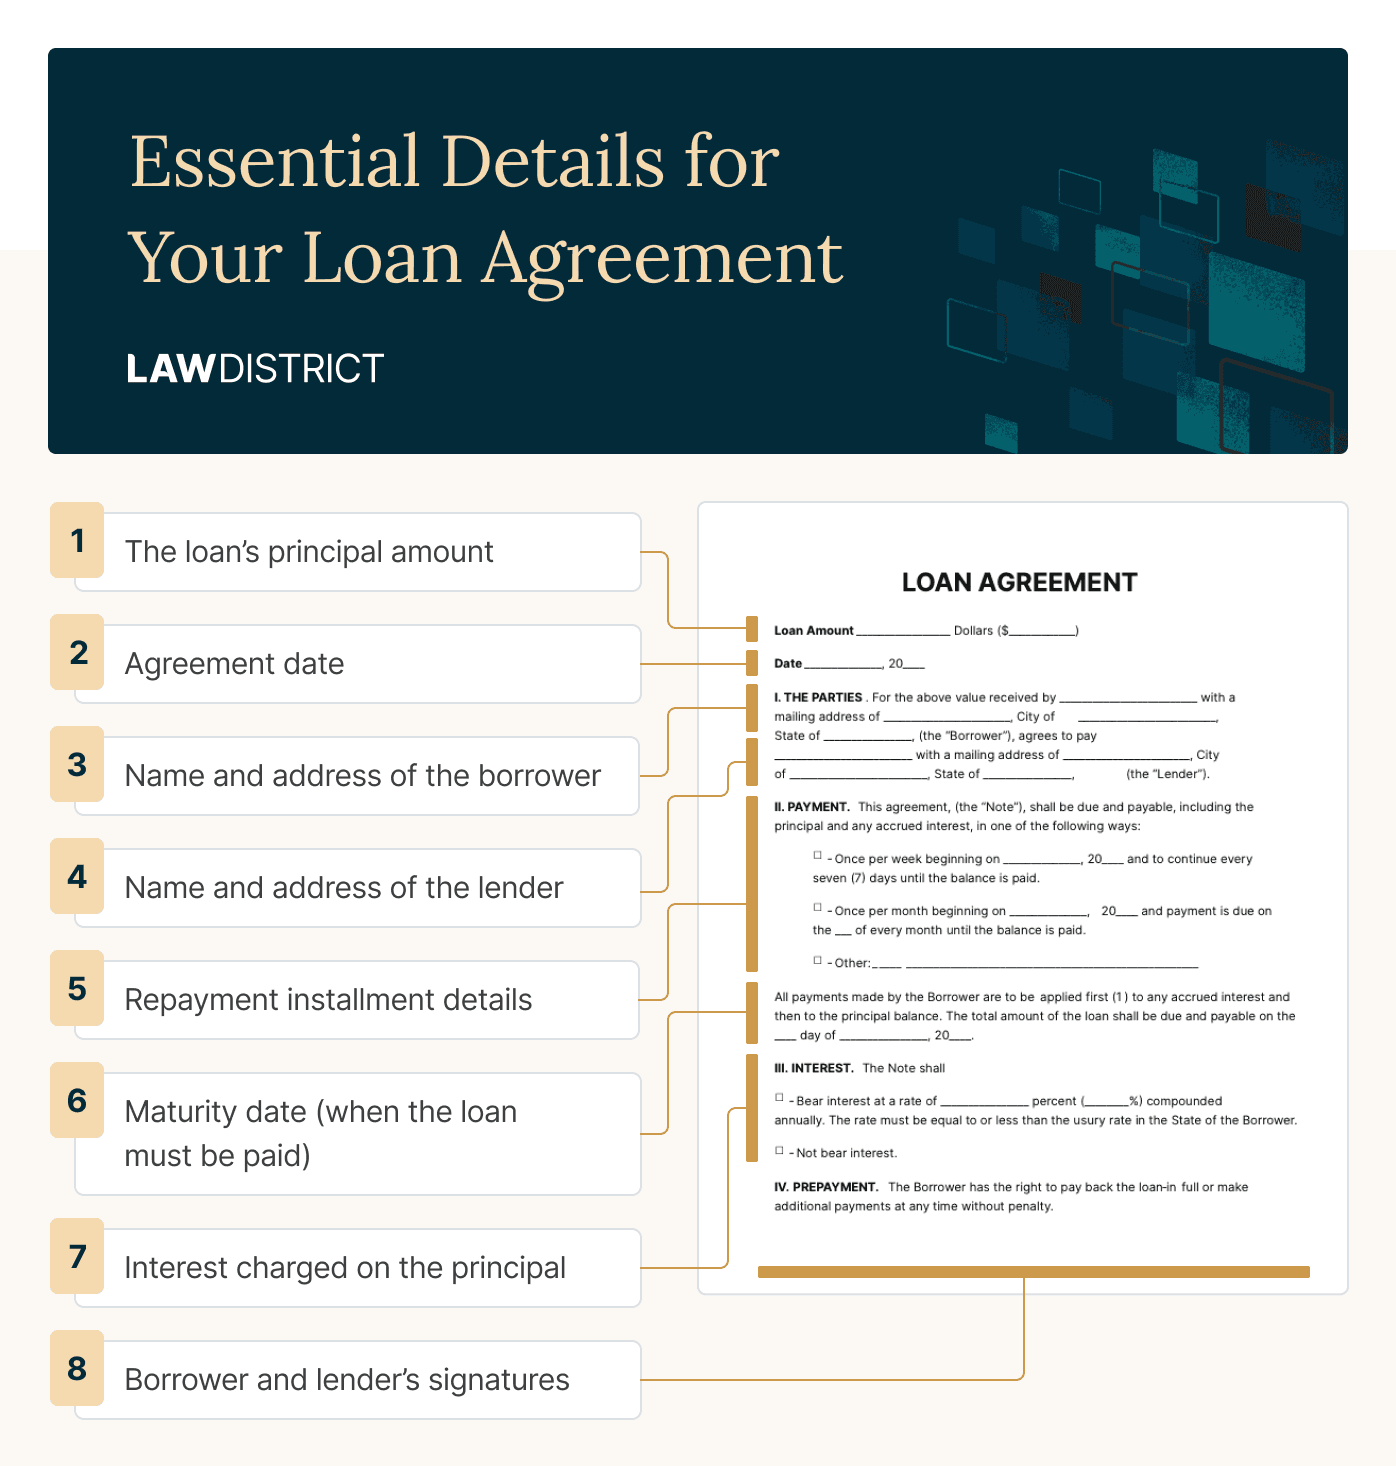
To correctly include these elements in your Loan Agreement, you must include the following loan details:
- Date of commencement: Include when the Loan Agreement will begin
- Parties: Enter the full names and complete addresses of both the Borrower and the Lender. It may also include Social Security and driver’s license numbers for identity verification.
- Loan Amount: Include the amount of money the lender will loan to the Borrower.
- Terms and Conditions: Add how the loan will be paid back (single payment, installments), acceptable payment forms (cash, money order, credit card, wire transfer, etc.), interest, collateral, origination fee, grace period, late fees, prepayment penalty fees, if any, amortization schedules, governing law, etc.
- Signatures: Sign the Loan Agreement with the other party, along with your name and date.
Use our Loan Agreement template as a helpful base to follow these steps better and create your document.
What Should I Include in a Loan Agreement?
Certain basic details must appear in your Loan Agreement no matter what. Failure to include crucial information could lead to your final form proving ineffective when it’s needed most.
The key contractual terms to remember in your Loan Agreement include the following:
- How much is being borrowed (sometimes referred to as the principal sum)
- If it is an unsecured loan or secured loan (a secured loan has a valuable item used as collateral to offset loan risk)
- When the money is being loaned and when it should be paid back
- The amount of interest that is to be charged
- If any late fees or pre payment penalties apply
- What should happen in the event of default by the borrower defaults on the amount
When you complete a Loan Agreement with our specialized advice, you will be prompted to provide these details.
Once complete, you can have your document reviewed by a legal professional to ensure it is ready.
How To Pay A Loan Agreement
Once a Loan Agreement has been finalized and the borrower has received the funds requested, they must follow the repayment schedule specified by the formal contract.
A borrower will often need to repay the loan in installments, usually paying either:
- Monthly payments
- Weekly payments
However, this is not the only possibility open to lenders and borrowers.
If the loan proceeds are smaller, the agreement might stipulate that the outstanding balance has to be paid in a single lump sum on a certain date or when the issuer requests the money back.
Additionally, some agreements will insist that some of the initial loan capital has to be returned via installments with a larger final payment made at the end of the contract (balloon payment).
This normally involves the interest being paid off via installments and the principal balance amount being paid back in full at the end [3].
What is an Amortization Schedule?
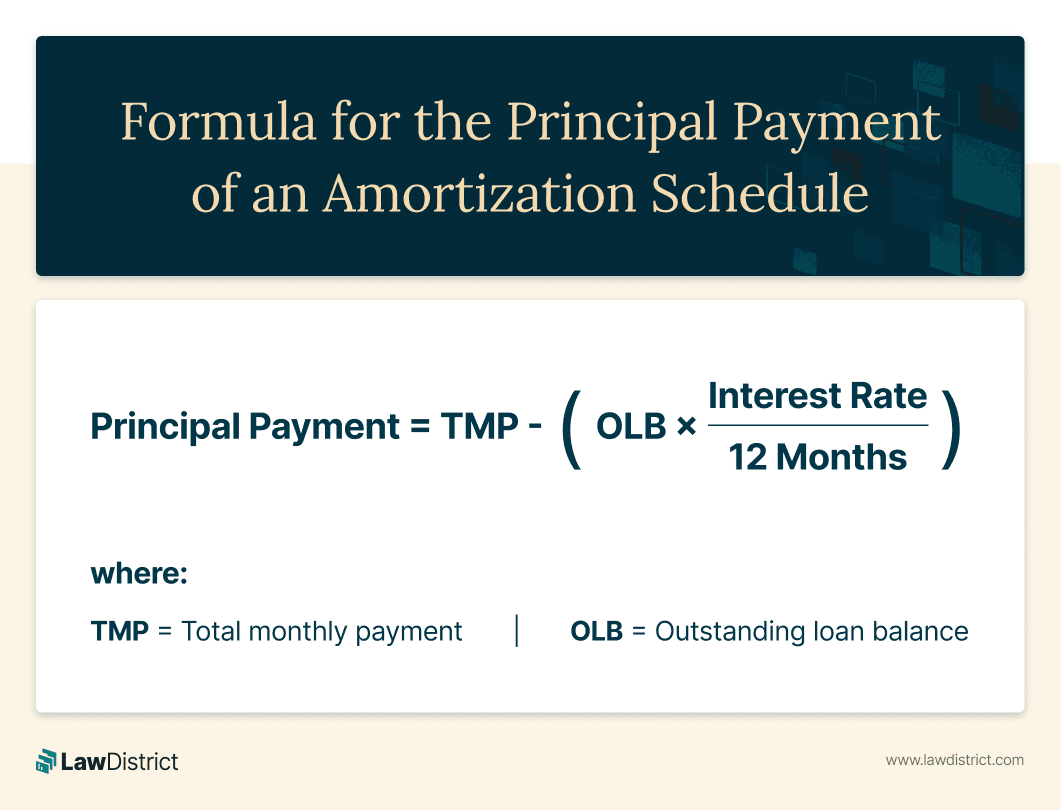
An amortization schedule is a table showing how each loan payment is divided between principal and interest over time. It also shows the remaining loan balance after each payment.
You can calculate your amortization payments using the following formula:
Understanding Default: What Happens If You Do Not Repay a Loan?
If a borrower does not make the required payments, the loan can go into default. The lender may demand the missed payments and, for loans secured by real estate, may eventually begin foreclosure if the borrower does not bring the loan current.
What is Foreclosure in the Context of a Loan?
Foreclosure is the process a lender uses to recover money owed on a defaulted mortgage or other real estate-secured loan by taking and selling the property.
It usually begins after missed payments and required notices. Foreclosure is generally a later step after the borrower has had an opportunity to address the default.
Judicial vs. Nonjudicial Foreclosure Processes
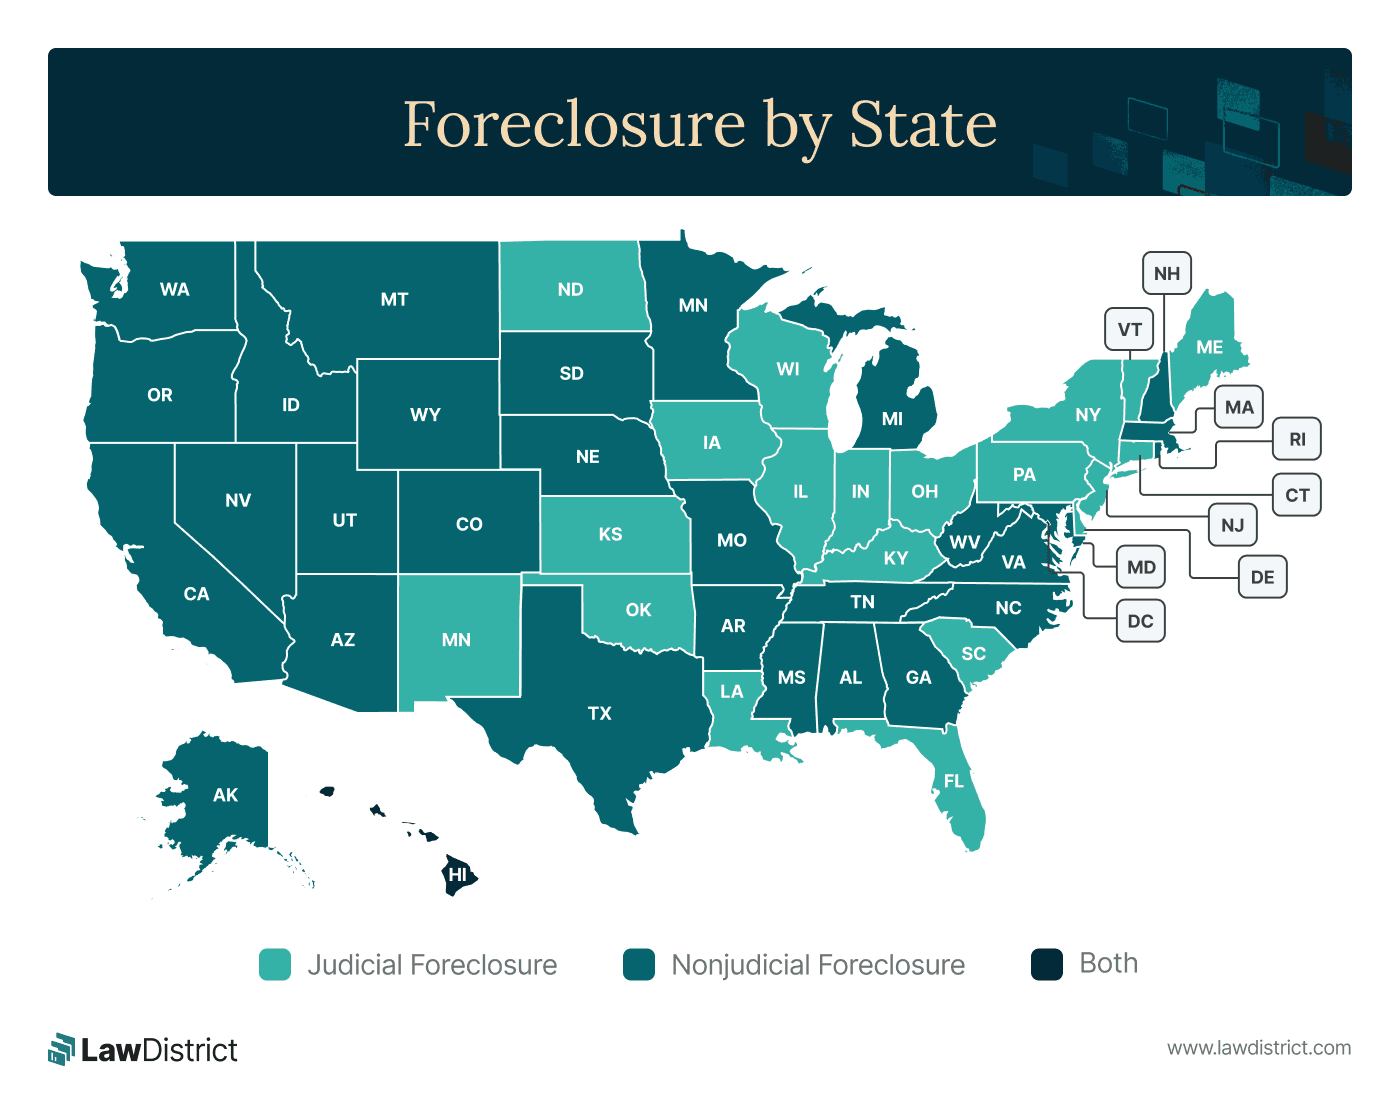
The foreclosure process depends on state law.
- Judicial foreclosure: The lender must go through the courts before the property can be sold.
- Nonjudicial foreclosure: The lender can use a statutory power-of-sale process without filing a foreclosure lawsuit.
You can see the type of foreclosure process of each each state below:
How To Sign a Loan Agreement
To sign your Loan Agreement, you should check with your jurisdiction to determine if there are any special requirements to fulfill before adding your signature.
In most cases, you are not legally obligated for the signing of the agreement to be witnessed, however, you may wish to sign the document in front of a:
- Notary public
- Witness
Loan Agreement FAQs
There are a lot of details about Loan Agreements that are essential to understand.
Find out what other key details you might need to consider before entering into a lending contract in our FAQs.
Use a Loan Agreement when lending money for real estate, businesses, student loans, or personal purchases. It ensures the borrower honors the deal and provides legal protection.
Always create and sign the agreement before transferring any funds.
A Loan Agreement and Promissory Note are often compared or even mentioned interchangeably.
While they are similar in certain aspects, the legal documents have some key differences.
Check the table below to understand the similarities and differences between the two documents.
| Loan Agreement | Promissory Note |
|---|---|
| There is a promise to repay | There is a promise to repay |
| Includes steps for repayment | Includes steps for repayment |
| There is a repayment timeline | There is a repayment timeline |
| Is legally binding | It is legally binding |
| Includes the signature of the borrower | Includes the signature of the borrower |
| Includes the lender’s signature | Does not include the lender’s signature |
| Can repay in installments | Cannot repay in installments |
| Includes consequences of not paying | Does not include consequences |
A Loan Agreement provides clarity and security, helping avoid disputes and defaults.
If a borrower makes late payments, decides not to pay or the lender changes the repayment terms suddenly, and there is no Loan Agreement, there is little either party can do to enforce the original accord. This could leave one side significantly out of pocket.
Anyone lending money should use a Loan Agreement. It is legally enforceable, providing a clear record of the loan terms and protecting both parties in case of disputes.
For borrowers, a Loan Agreement specifies the repayment schedule and interest rates, ensuring transparency and protection against predatory practices and unexpected changes.
The principal sum is the amount of money you originally borrow before any interest or other charges are added.
As you make payments, the outstanding principal usually decreases until the loan is fully repaid.
The annual percentage rate (APR) shows the yearly cost of borrowing as a percentage. It can include the interest rate plus certain fees and charges.
It’s useful for comparing the overall cost of different loans.
The main difference is what each percentage includes:
- Interest rate: The cost of borrowing the principal amount.
- APR: The interest rate plus certain loan fees and charges.
For this reason, the APR may give you a broader picture of the loan’s total annual cost.
The Truth in Lending Act (TLA) is a law that requires U.S. financial institutions to disclose their APR before signing any loan agreement with a borrower.
The intent of the TLA is to protect borrowers from misleading advertising.
Try Lawdistrict Now
Instant and complete access to our entire library of legal forms
Edit, download and print in PDF from any device
Save time and money on legal document creation